An SBA 504 loan is a two-part financing structure for owner-occupied commercial real estate and heavy equipment, combining a conventional bank first mortgage with a government-guaranteed second mortgage originated through a Certified Development Company. The appeal is straightforward: a long fixed rate on the second position and a low equity requirement compared with standard commercial mortgages.
The complication is that the 504 structure has rules most borrowers do not discover until underwriting. Occupancy thresholds, restrictions on eligible costs, job-creation or public-policy tests, and the timing of the bond sale all shape what a project can actually support. This guide explains how the pieces fit, where the structure outperforms a single-lender loan, and where it quietly costs more than expected.
Key takeaways
- The program pairs a third-party bank or credit union first mortgage with a Certified Development Company second mortgage funded by a bond sale, plus a borrower equity injection that is usually at least 10 percent.
- Proceeds are limited to long-lived fixed assets such as owner-occupied buildings, land, new construction, and heavy equipment, not working capital or inventory.
- Owner-occupancy rules matter: existing buildings generally require the business to occupy at least 51 percent of the space, and new construction generally requires 60 percent initial occupancy.
- Special-purpose properties, startups, and hotel projects typically require a larger down payment, often 15 to 20 percent.
- The CDC portion carries a fixed rate set when the bond is sold, so the pricing you model at application is not final until funding.
What Is an SBA 504 Loan and How Does It Work?
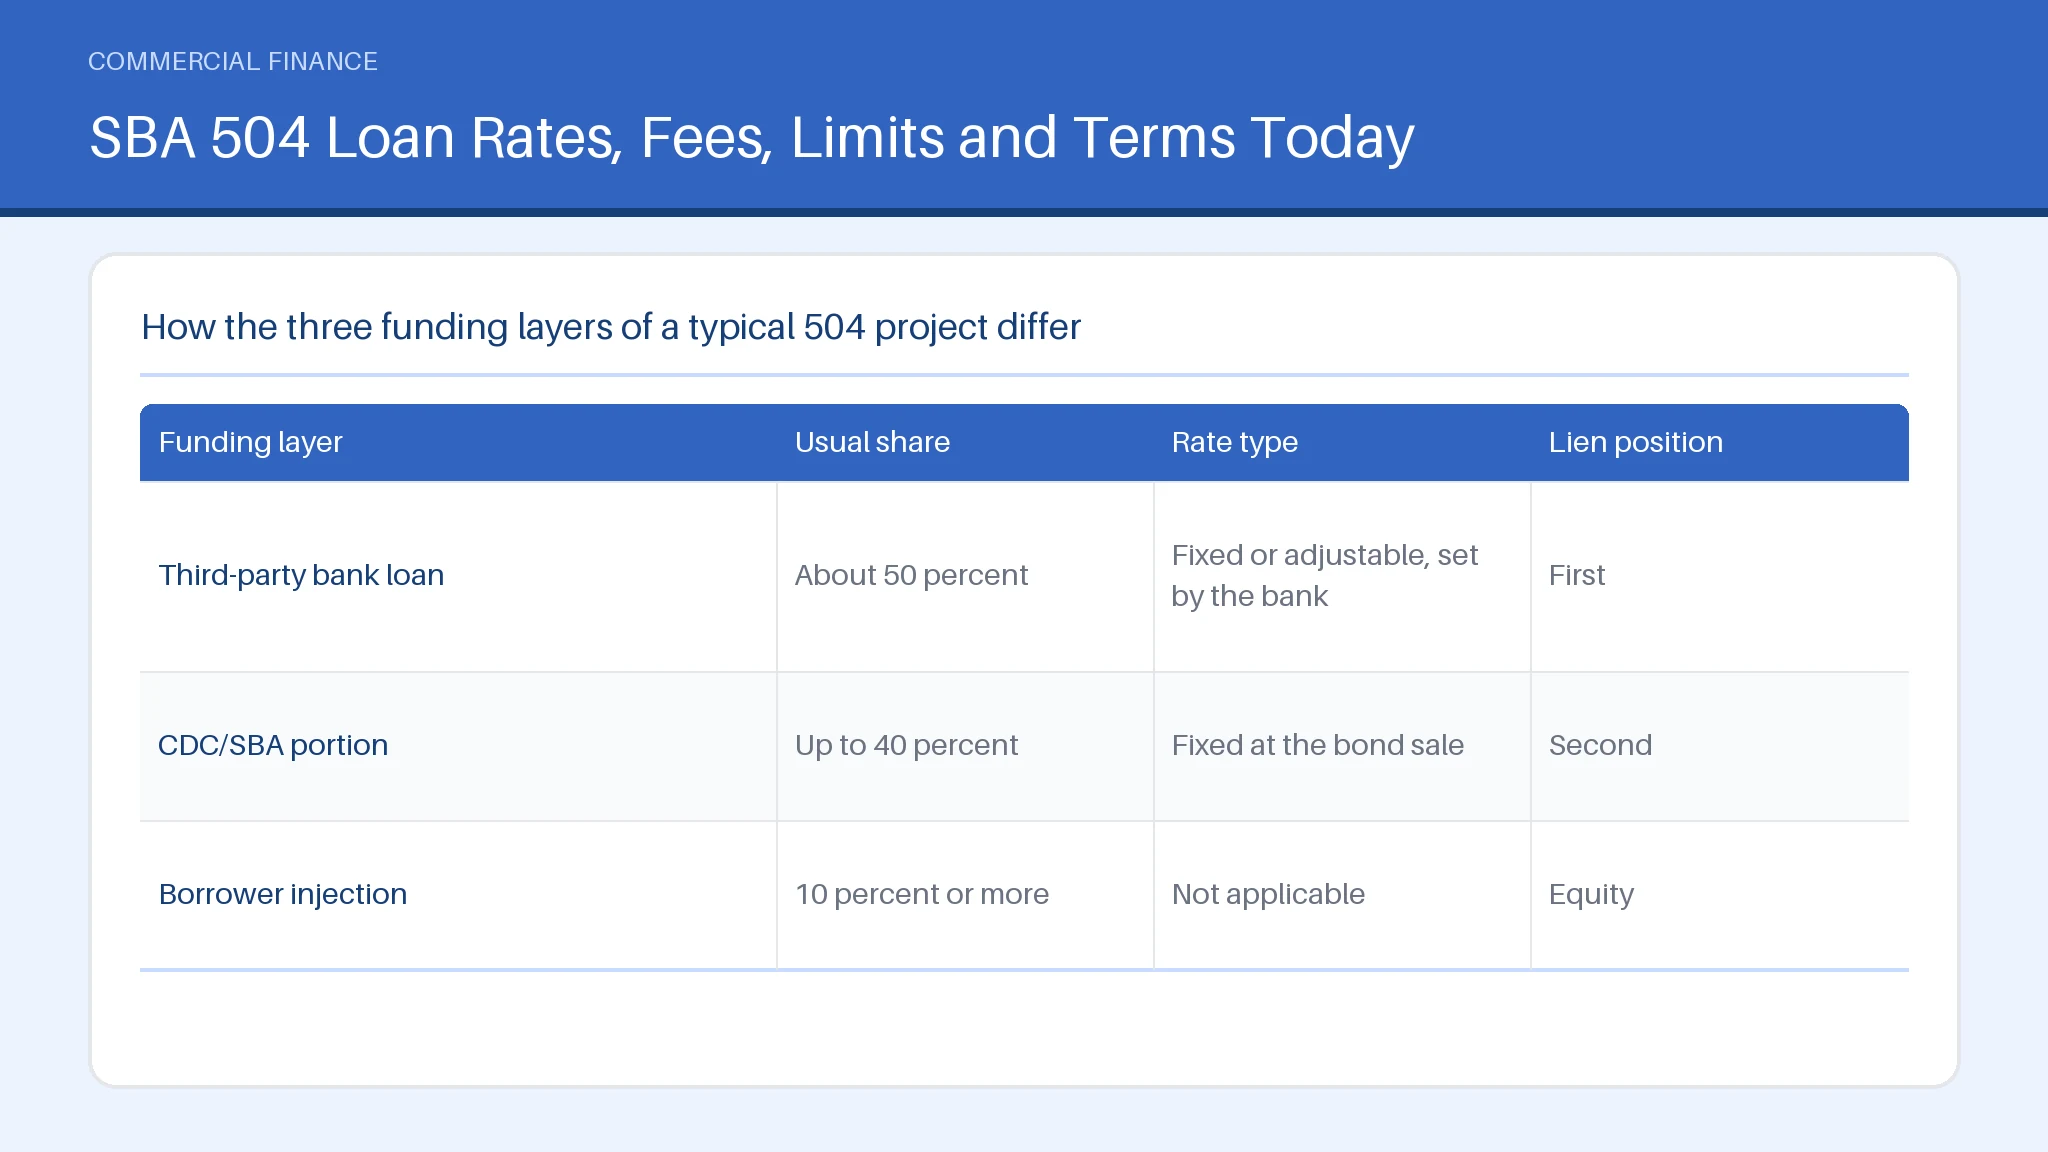
| Funding layer | Usual share | Rate type | Lien position |
|---|---|---|---|
| Third-party bank loan | About 50 percent | Fixed or adjustable, set by the bank | First |
| CDC/SBA portion | Up to 40 percent | Fixed at the bond sale | Second |
| Borrower injection | 10 percent or more | Not applicable | Equity |
Managing an Existing SBA 504 Loan and Tracking Payoff
Servicing runs on two tracks, and owners regularly forget this. The bank services its first mortgage, while a central servicing agent collects the CDC payment and applies it to the debenture pool. Payoff quotes therefore come from two places, and the second-position payoff can include a prepayment premium during the first half of the term because the underlying bond has a fixed maturity.
Keep a running schedule of each fix asset pledged, its remaining book value, and the approve date on any subordination or lease change, since both lenders must consent before a pledged asset is sold. Owners who later want to refinance, expand, or qualify for a second project, including sba 504 hotel loans or another loan dayton oh transaction, need clean payoff records first.
Sba 504 loan dayton oh should be matched to the skin concern, current tolerance, and whether medical review is needed before changing active ingredients.
How to Apply for SBA 504 Financing Step by Step
Underwriting, appraisal, environmental review, and SBA authorization follow, then closing. Every fix asset in the budget must be documented. Financing timelines usually run 45 to 90 days, and financing for construction takes longer because draws are inspected. A lender handling an loan cincinnati oh or sba 504 hotel loans request will confirm eligible costs before financing terms are issued.
SBA 504 Loan Rates, Fees, Limits and Terms Today
Loan collateral requirements should be matched to the skin concern, current tolerance, and whether medical review is needed before changing active ingredients.
Why 504 Borrowing Feels Simpler for Small Business Owners
Predictability is the real draw. A fixed second mortgage over 25 years removes most interest-rate risk from the largest line on the balance sheet, and owners can model occupancy costs for a decade instead of bracing for a balloon. The same program covers machinery with a useful life of 10 years or more, so a plant expansion and its equipment travel together.
Eligibility is also mechanical rather than subjective. The CDC will certify the size standard, the job or public-policy test, and the occupancy share, then approve or decline against published rules. Loan collateral requirements rarely reach outside the project, and an sba 504 construction loan or an loan toledo oh purchase follows the same checklist. Existing 504 debt can also refinance under specific conditions.
Cybersecurity Basics Every Small Business Borrower Should Practice
Loan files are a fraud target because they concentrate tax returns, bank statements, and wire instructions in one thread. Use a secure portal rather than plain email attachments, enable multi-factor authentication on business banking and accounting software, and verify every wire instruction by calling a number you already have on file, never one supplied in an email.
Loan toledo oh should be matched to the skin concern, current tolerance, and whether medical review is needed before changing active ingredients.
Summary
The 504 program trades two approvals and slower timing for low equity and a long fixed second mortgage on owner-occupied fixed assets. CRE Loans USA is a lender-matching service, so describing your project routes the details to independent providers who make their own decisions. continue with the qualification form below.
Frequently asked questions
How does a 504 SBA loan work?
A 504 loan funds a project in layers. A bank lends about 50 percent in first position, a Certified Development Company lends up to 40 percent in second position using proceeds from a government-guaranteed bond, and you contribute the remainder as equity. Both loans are secured by the project assets and close together, though the CDC portion is funded shortly after.
Is it hard to get an SBA 504 loan?
Approval is demanding but predictable, because Loan requirements are published rather than discretionary. Core requirements include the cash injection, documented repayment ability from business cash flow, acceptable credit, a for-profit business within the size standard, and meeting occupancy and job or public-policy tests. Startups and special-purpose properties face higher equity expectations, so difficulty depends more on project type than paperwork volume.
What are SBA 504 loan rates today?
Pricing on the second-position portion is fixed when the monthly bond is sold, so the rate is set by market conditions in that month rather than quoted in advance. The first mortgage is priced separately by the bank. Independent providers publish current pricing; no one can promise a rate before the bond sale settles.
What is the difference between a 7A and 504 SBA loan?
The 7(a) program is flexible and covers working capital, inventory, business acquisition, and real estate with a variable rate in most cases. The 504 program is narrower, funding only long-lived fixed assets, but offers a long fixed rate and a lower down payment. Many owners use 7(a) for operations and 504 for buildings.
What are the disadvantages of one?
Drawbacks include a longer timeline, two lenders and two closings, restrictions on eligible uses, prepayment premiums in the early years of the CDC portion, and occupancy rules that limit how much space you can lease out. Projects that need speed or working capital are often better served by other structures, including the options covered in our finance guides.
What is the maximum amount for a 504 loan?
The CDC portion is generally capped at $5 million, rising to $5.5 million for qualified manufacturers and certain energy-efficiency projects. Because the bank share is uncapped, total project size can exceed $10 million or more when the first mortgage is large enough.
Can you pay off one early?
Early payoff is allowed, but the CDC portion usually carries a declining prepayment premium during roughly the first half of its term, reflecting the fixed-maturity bond behind it. The bank first mortgage has its own terms. Request written payoff figures from both servicers, and review our general financing questions for related context.
You may also find these related guides helpful: dscr loan requirements terms and how approval works and cap rate real estate formula examples and noi.